


Home » Sample Letter to Cancel Merchant Services (Free Word & Google Docs Templates)
Sample Letter to Cancel Merchant Services (Free Word & Google Docs Templates)
| November 13, 2026
If you plan to cancel merchant services or switch providers, it is often not enough to simply send an email to your payment processor. Many providers require a written cancellation request, and some may also ask you to complete and sign an official account closure form.
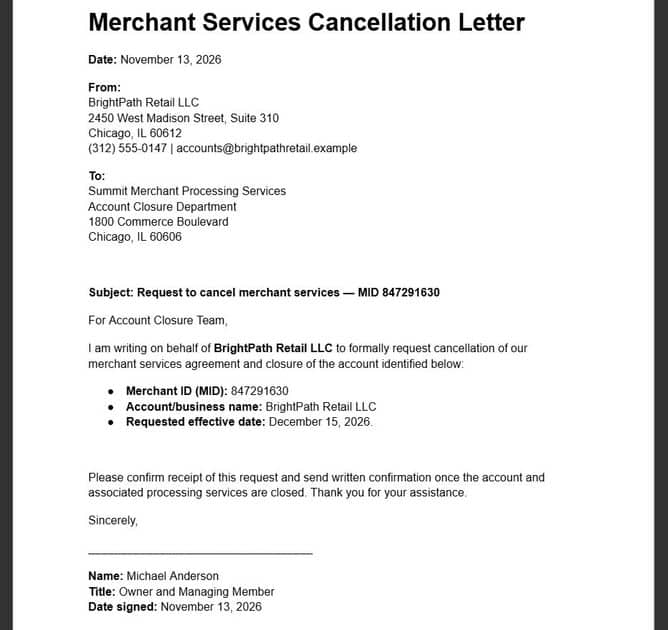
To speed things up, we’ve prepared a sample letter to cancel merchant services that contains general information required to send to your provider. You can download the free Word or Google Docs template below.
An example of a merchant services cancellation letter
A merchant services cancellation letter is a formal written request to close your merchant account and terminate your payment processing services. The letter should identify your business and merchant account, specify your requested cancellation date, and ask the provider to confirm the closure in writing.
Before sending your letter, keep a few important things in mind:
- Check your provider’s cancellation requirements: Most providers require you to complete and sign their official account closure form.
- Review your contract: Check the required notice period (it’s often 30 days), potential early termination fees, closure fees, and any conditions that could affect your requested cancellation date.
- Use the correct submission method: Your provider may require you to submit the request through a specific email address, online portal, or other designated channel.
- Keep proof of your request: Save a copy of the signed letter, evidence of submission, and any written confirmation you receive.
- Address outstanding obligations: Closing your merchant account does not eliminate outstanding processing fees, chargeback liabilities, or reserve requirements. For example, Stripe confirms that merchants remain responsible for certain account liabilities after closure.
Our sample letter is a general-purpose template, not a substitute for your provider's official cancellation procedure. Contact your payment processor if you're unsure whether a written letter is sufficient to initiate account closure.
Use our free merchant services cancellation letter template
To make the cancellation process easier, we’ve created a free, customizable merchant services cancellation letter you can use as an editable template when formally requesting closure of your merchant account.
Choose your preferred format:
- Download the Word template → Edit the letter in Microsoft Word and save it as a DOCX or PDF before submitting it.
- Google Docs template → You will be automatically prompted to make a copy of the document so we can save the original intact. Again, edit/fill out your copy and save it as a PDF before sending it to your provider.
How to use the template: Simply replace the bracketed placeholders with your business information, provider details, and requested cancellation date. You can also adjust the wording to include additional information required by your payment processor.
The template includes requests for written confirmation of account closure, a breakdown of any outstanding charges, and information about the release of remaining funds or reserves.
Important: Before submitting your letter, check whether your provider requires a specific cancellation form or submission method. If so, follow those instructions and use our template as supporting documentation where appropriate.
FAQs about canceling merchant services
Canceling merchant services can be a touchy subject, as it is a consequential decision that affects day-to-day operations and involves sensitive business information.
Below, we try our best to answer the most common questions we get from merchants about cancellation letters, potential fees, processing times, and account closure procedures.
What to include in a merchant services cancellation notice?
A merchant services cancellation notice should clearly identify your business, specify which account you want to close, and formally request the termination of your payment processing services.
Your cancellation letter should generally include:
- Business information: Your legal business name, address, and contact details.
- Merchant account details: Your merchant identification number (MID) and the name of your payment processing provider.
- Cancellation request: A clear statement that you want to terminate your merchant services agreement and the reason why.
- Requested cancellation date: The date you want your services to end, taking into account any contractual notice requirements.
- Authorized signature: The name, title, signature, and date of the business owner or another authorized representative.
- Confirmation request: A request for written confirmation of the cancellation date and any outstanding fees or obligations.
Some payment processors require additional information, such as a reason for cancellation or an official account closure form. You can usually find these requirements in your merchant services agreement, provider’s help center, or account management portal.
Keep your cancellation letter short, professional, and direct. You do not need to provide a lengthy explanation for leaving unless your provider specifically requires one.
How much does it cost to cancel merchant services?
The cost of canceling merchant services depends on your provider, your merchant services agreement terms, and any outstanding financial obligations.
Some providers offer agreements with no early termination fees, while others charge $200–$500 or more for ending a contract early. Merchant agreements with liquidated damages clauses can be significantly more expensive, potentially costing thousands of dollars depending on the remaining contract term.
Technically, most agreements have a 3-year term. Due to our business model, relationships, and the quality of service provided, we can get 9 out of 10 customers out of this agreement with no penalties, depending on the circumstances. All terms and closure fees will always be located in the merchant agreement initially signed.
Below is an extensive list of potential costs. It’s unlikely that all of them will apply to you.
| Potential cost | Typical cost range | When it applies |
|---|---|---|
| Early termination fee | $200–$500 for many flat-fee agreements | If you cancel a fixed-term merchant services agreement before it expires. The fee may be a flat amount or calculated based on the remaining contract term. |
| Monthly service fees | $10–$50+ per month until cancellation | If your agreement requires advance notice, you may continue paying monthly account, gateway, or other service fees until the cancellation becomes effective. |
| Equipment lease termination | Remaining lease payments if applicable; can be in hundreds or thousands of dollars | If you lease payment terminals or other processing equipment under a separate agreement. You may owe remaining lease payments or an early termination charge. |
| Outstanding processing fees | Remaining lease payments if applicable; can be in hundreds or thousands of dollars | If you lease payment terminals or other processing equipment under a separate agreement. You may owe remaining lease payments or an early termination charge. |
| Outstanding processing fees | Varies based on transaction volume and unpaid charges | If you have unpaid transaction fees, monthly minimums, or other processing charges incurred before your account closes. |
| Chargeback fees | Often$15–$30 per chargeback, plus the disputed amount | If customers dispute transactions processed before cancellation. |
| Reserve deductions | Varies based on the reserve balance and outstanding liabilities | If your processor maintains a rolling reserve or other held balance to cover potential losses. |
While some merchant services agreements come with cancellation costs, don’t let potential fees discourage you from switching providers. If you’re dealing with high processing rates, fund holds, unreliable service, or unfavorable contract terms, switching to a more reliable provider will save you significantly more money (and nerves) in the long run.
Before submitting your cancellation request, you should review your merchant services agreement and ask your provider for a breakdown of any applicable charges.
How long does merchant account cancellation take?
The merchant account cancellation process can take anywhere from a few business days to several weeks, depending on your provider’s procedures, contractual notice requirements, and whether you have any outstanding obligations.
Some providers will close accounts quickly, while most will require 30 – 45 days or more of advance notice before termination takes effect.
However, closing your merchant account doesn’t necessarily mean you’ll receive all your remaining funds immediately. Final transaction settlements, outstanding chargebacks, and reserve requirements can affect when your money becomes available. For instance, if your provider holds a rolling reserve, the remaining funds may not be released for several months after account closure.
To avoid unnecessary delays, review your cancellation terms, resolve outstanding issues, and ask your provider to confirm both the expected account closure date and the timeline for releasing any remaining funds.
What is the process for canceling merchant services?
Canceling merchant services involves reviewing your agreement, notifying your payment processor, settling outstanding obligations, and confirming your account is officially closed.
Here are the seven steps you should follow:
- Review your merchant services agreement: Check your contract for cancellation requirements, notice periods, early termination fees, and equipment return obligations. Pay particular attention to automatic renewal clauses.
- Contact your merchant services provider: Notify your provider that you want to cancel your account. Ask whether you need to submit a written cancellation letter, complete an official closure form, or follow another specific procedure.
- Settle outstanding transactions: Make sure pending payments have been processed, and outstanding refunds are addressed. Download any transaction records, statements, or reports you may need after closing your account.
- Address rolling reserves and outstanding liabilities: Confirm how your provider will handle held funds, outstanding processing fees, and potential chargebacks after cancellation. Ask when you can expect any remaining reserve funds to be released.
- Return payment processing equipment: If you rented or leased payment terminals or other equipment, check whether you need to return them. Follow the provider’s return instructions and keep proof of shipment or delivery.
- Obtain written cancellation confirmation: Ask your provider to confirm your account closure date, any remaining charges, and whether additional action is required on your part.
- Monitor your account after cancellation: Review your final processing statements and bank account activity to identify unexpected charges. Contact your former provider if you notice fees that don’t match your agreement.
If you're moving to another payment processor, set up and test your new merchant account before terminating your existing services to avoid unnecessary payment processing downtime.
For a more detailed breakdown, read our guide on how to switch merchant services providers.
Need a better provider? Switch to SecureGlobalPay
Are you sick and tired of high processing fees, poor customer support, constant fund holds, and unfavorable contract terms?
SecureGlobalPay is a full-service merchant services provider specializing in payment processing solutions for high-risk businesses. We help merchants secure reliable payment processing and merchant accounts with competitive rates and dedicated support.
Here’s why businesses choose SecureGlobalPay:
- Competitive, transparent pricing: Get affordable processing rates with no setup fees, hidden charges, or early termination fees. Most merchants opt for interchange-plus pricing.
- Fast approvals and funding: Get your merchant account approved quickly and access same-day and next-day funding when eligible.
- High-risk merchant account expertise: We partner with acquiring banks that support high-risk, high-volume, and other hard-to-place merchants.
- 200+ platform integrations: Our PCI-compliant payment gateway connects to most e-commerce platforms, shopping carts, invoicing tools, and other business software.
- Advanced fraud and chargeback protection: Reduce payment risks with AI-powered fraud detection, 3D Secure authentication, chargeback management tools, and more.
- Flexible payment acceptance: Accept payments online, in person, over the phone, or through recurring billing, depending on your business needs.
- Dedicated account management: Each merchant gets personalized assistance from an experienced U.S.-based account manager via phone or email.
Partner with a merchant services provider that actually wants your business.
Apply online today to get started and sign up with SecureGlobalPay.
Written by Roland G. Szasz - Director of Business Development - 25+ years in payment processing.
Roland has spent nearly three decades helping businesses navigate the complexities of payment processing. He now works closely with high-risk merchants that have been declined or restricted by conventional providers - and shares his experience and best practices on this blog.

Posted in - Business Advice for Merchants, Merchant Accounts
Tailored payment solutions for high-risk merchants
- Domestic and offshore accounts
- Competitive, interchange plus pricing
- No long-term contracts or hidden fees
- Built in fraud protection
- Dedicated account manager; 24/7
Sign up in 5 minutes
A+ Rating
as of 06/17/26