


Home » How to Write a Chargeback Rebuttal Letter (Free Template & Examples Included)
How to Write a Chargeback Rebuttal Letter (Free Template & Examples Included)
| November 20, 2026
Getting a chargeback doesn’t always mean you have to accept the loss. If you believe a customer has disputed a legitimate transaction, you can challenge the chargeback by submitting a response backed by relevant evidence.
A chargeback rebuttal letter is your opportunity to explain what happened, address the customer’s claim, and present the facts that support your case.
In this guide, we’ll show you how to write an effective rebuttal letter, what evidence to include, and how to submit your chargeback response. You’ll also find a free chargeback rebuttal letter template and actual examples for the four most common types of disputes.
Download your free chargeback rebuttal letter template
You don’t have to write your chargeback rebuttal letter from scratch. We’ve prepared a free, customizable template that includes all the essential sections — from transaction details and the reason for the dispute to your explanation, supporting evidence, and formal request for reversal.
Choose your preferred format:
- Download the chargeback rebuttal letter template (Word)
- Download the chargeback rebuttal letter template (PDF)
- Get a copy of the chargeback response template (Google Docs) → You will be automatically prompted to make a copy of the document so we preserve the original.
Here’s a quick preview of the template:
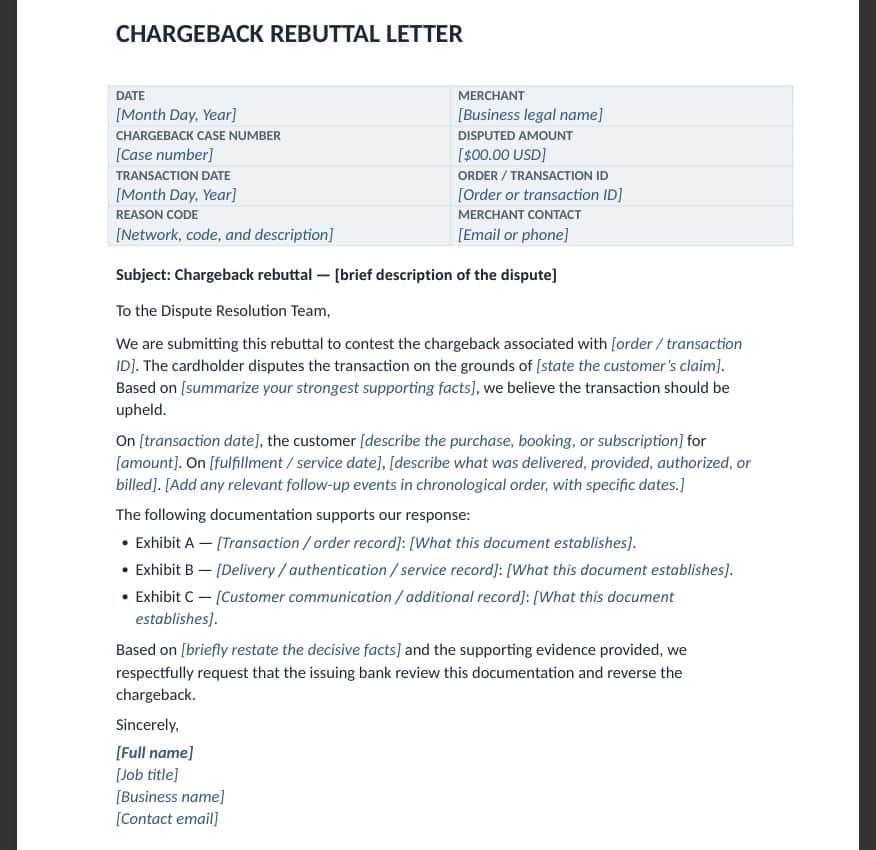
To customize it, simply replace the placeholder text with your transaction details, explain why the customer’s claim is incorrect, and reference the evidence supporting your position. Remove any details that don’t apply to your case.
Not all chargebacks are the same. The template provides a useful starting point, but your response should always address the specific dispute reason and follow your payment processor's submission requirements.
What is a chargeback rebuttal letter?
A chargeback rebuttal letter is a written statement in which a merchant explains why a disputed transaction is valid and why the chargeback should be reversed.
Merchants typically submit rebuttal letters as part of the chargeback representment process — the formal procedure for challenging a chargeback by providing evidence to the cardholder’s issuing bank.
A well-written chargeback rebuttal letter serves three main purposes:
- Summarizes the transaction: Identifies the disputed payment, including the transaction date, amount, and relevant order details.
- Addresses the customer’s claim: Explains why the merchant (you) believes the chargeback is invalid, using specific facts rather than assumptions.
- References supporting evidence: Points to receipts, delivery confirmations, customer communications, authentication records, or other documentation that supports the merchant’s position.
The rebuttal letter is only one part of the chargeback response “package”. The complete package typically includes the letter alongside supporting documents that help the issuing bank evaluate the dispute.
Simply sending a rebuttal letter alone does not guarantee a successful outcome. The strength of your evidence, the applicable chargeback reason code, and the card network’s dispute rules all influence whether a chargeback can be reversed.
How to write a chargeback rebuttal letter
An effective chargeback rebuttal letter should be concise, factual, and focused on the specific reason for the dispute. Your goal is to explain why the transaction was valid and make it easy for the reviewer to verify your claims using the attached evidence.
Follow these six steps to prepare a clear, well-supported chargeback response.
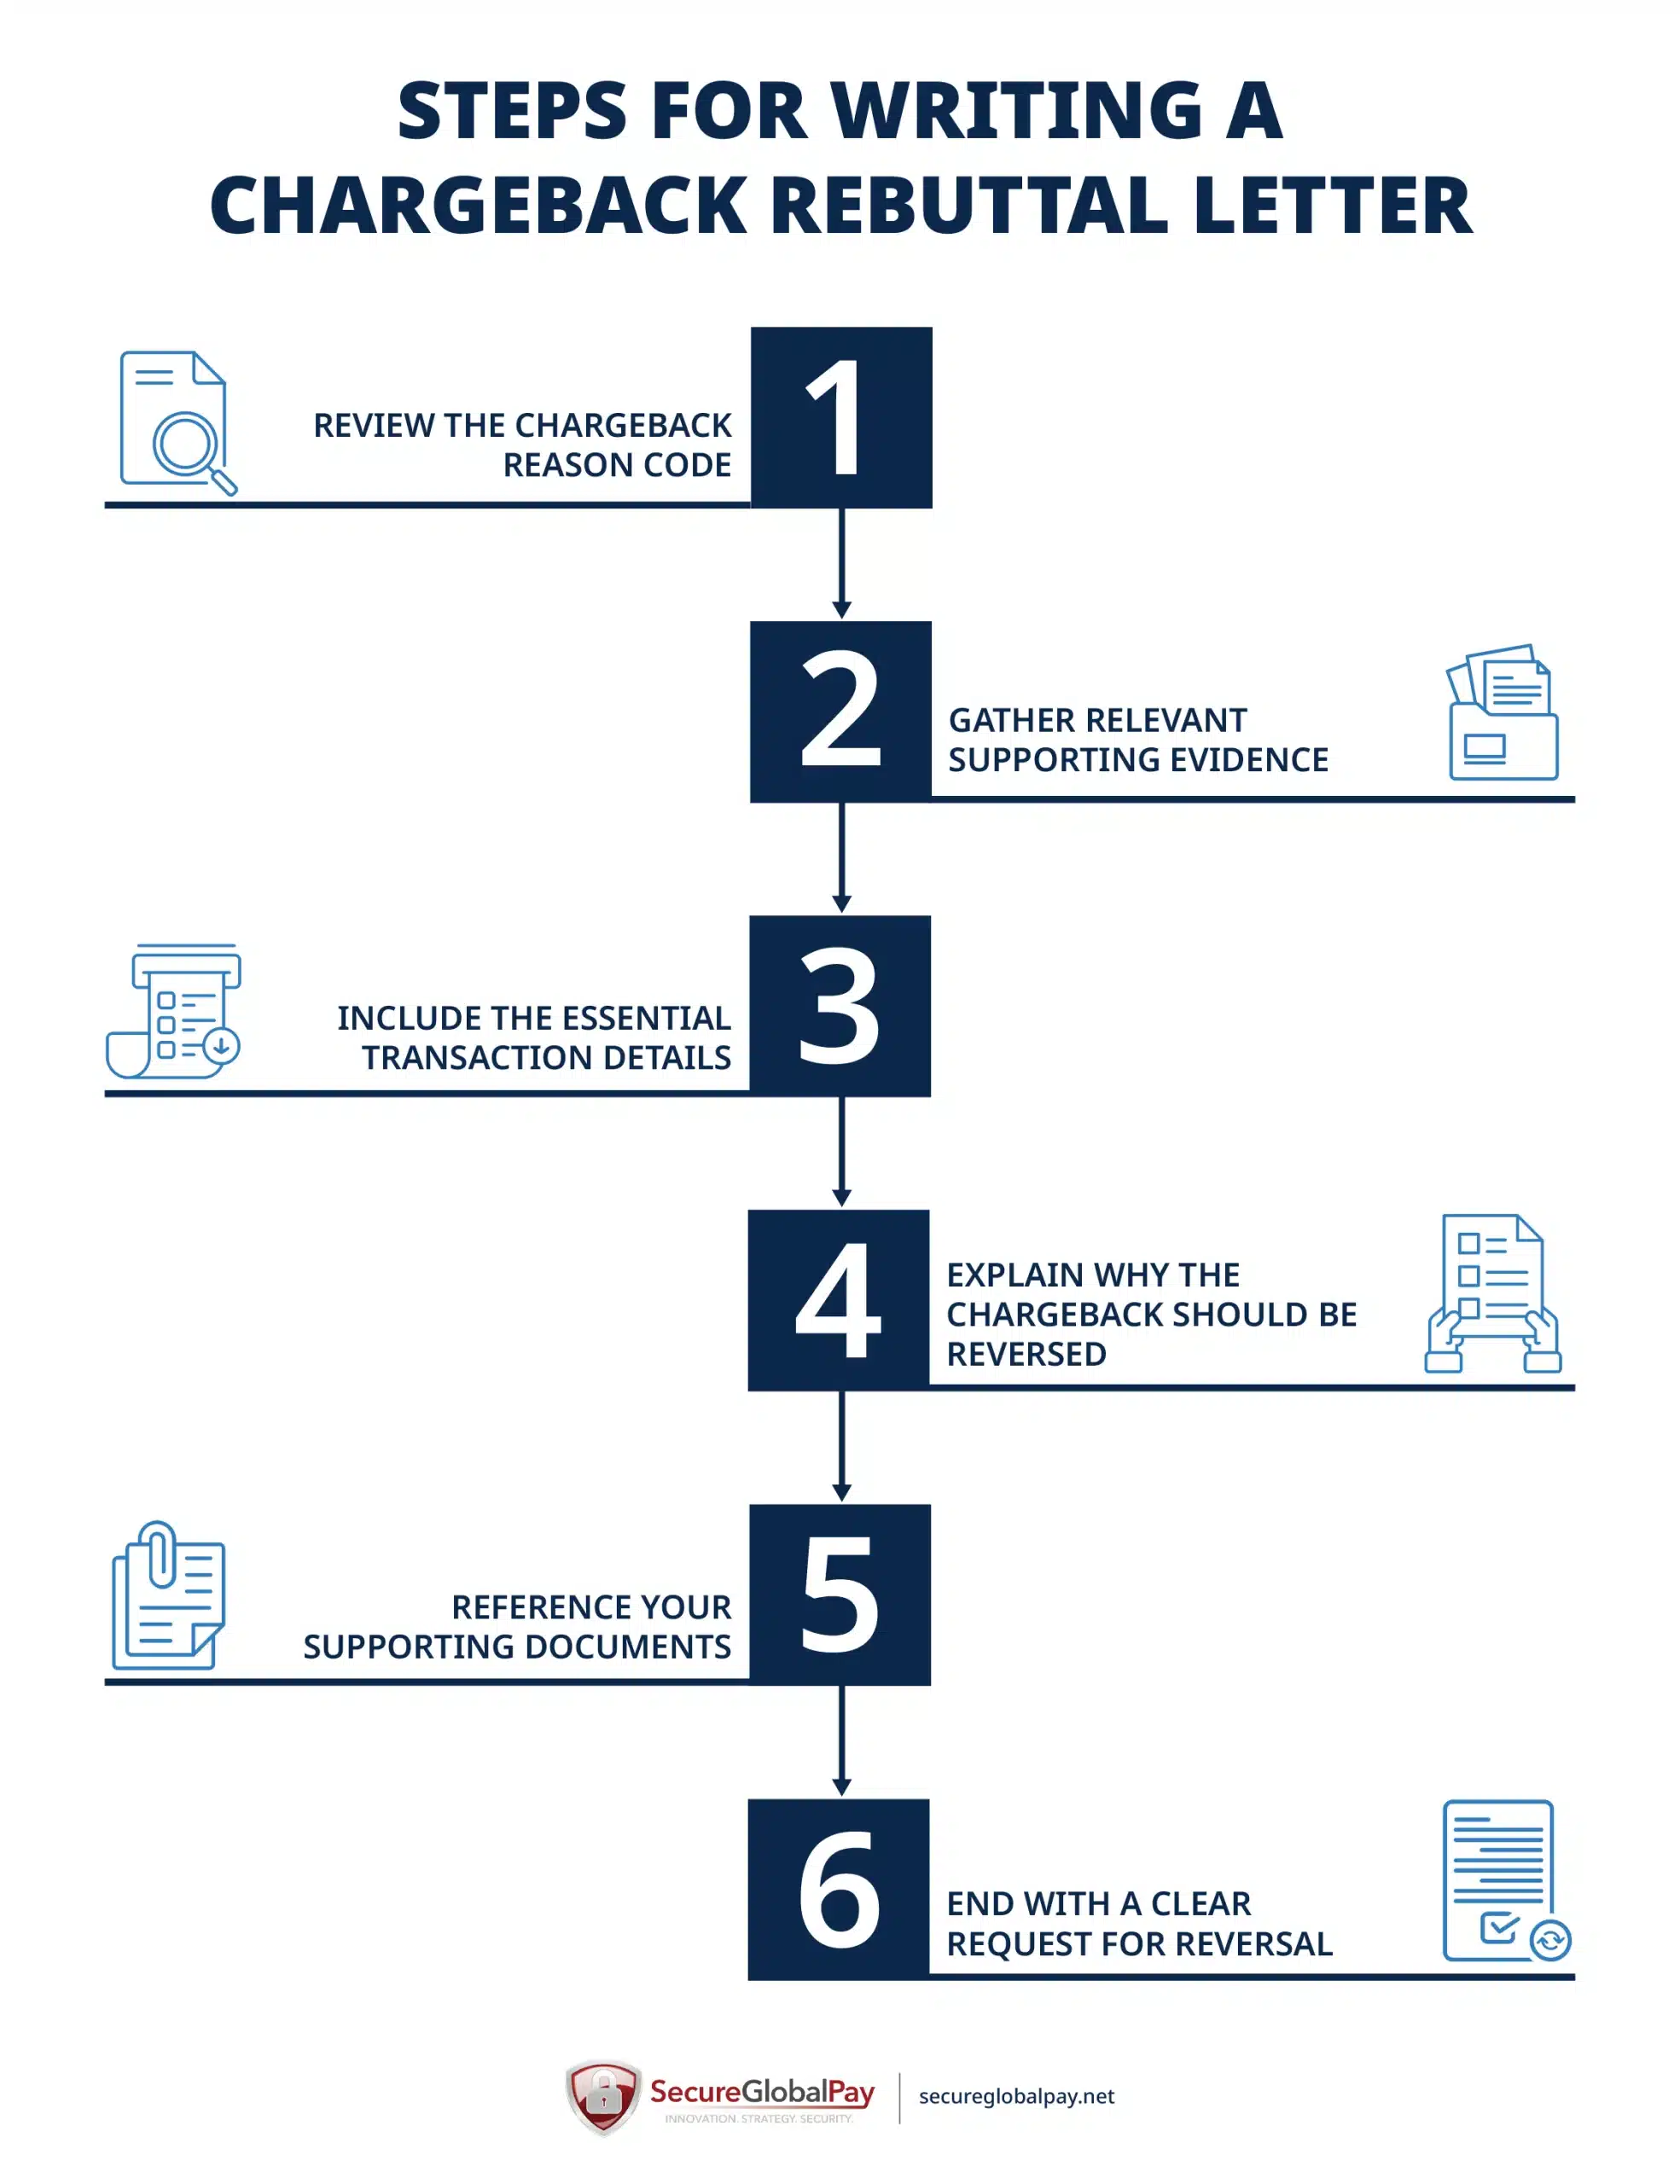
Step 1: Review the chargeback reason code
Before writing your rebuttal letter, check the chargeback reason code provided in the dispute notification from your payment processor or acquiring bank.
A chargeback reason code identifies the type of dispute and helps you understand why the cardholder is challenging the transaction. For example, a customer might claim they never authorized the payment, didn’t receive their order, or were charged after canceling a subscription.
Each dispute type requires a different approach. Proof of delivery might help challenge a merchandise-not-received dispute, but it generally won’t be sufficient to overturn an unauthorized transaction claim.
Visa and Mastercard use different reason codes and have specific rules about which evidence merchants can submit for each dispute. For detailed guidance, consult the official Visa dispute management guidelines or Mastercard’s chargeback dispute guide
Step 2: Gather relevant supporting evidence
Once you understand the chargeback reason, collect documentation that directly addresses the customer’s claim. The strongest chargeback responses rely on relevant, verifiable evidence. Overwhelming the reviewer with a bunch of unrelated records will only work against you.
The type of evidence you need depends on the dispute reason:
| Chargeback reason | Relevant supporting evidence |
|---|---|
| Unauthorized transaction | Authentication records, 3D Secure results, AVS/CVV verification results, and qualifying transaction history. |
| Product not received | Shipping records, tracking information, proof of delivery, and customer communications. |
| Product not as described | Original product descriptions, photographs, order details, and customer communications. |
| Subscription canceled | Subscription agreement, cancellation policy, billing records, and cancellation confirmation or logs. |
| Credit not processed | Refund receipts, transaction history, credit processing records, and proof of refund. |
Evidence requirements vary by card network and specific chargeback reason code. Some types of evidence may only be considered when additional eligibility conditions are met. For example, for Visa’s merchandise-not-received disputes (reason code 13.1), proof of delivery should include the full delivery address, not just a tracking status showing “delivered.”
Before drafting your letter, organize the relevant documents, check that transaction dates and amounts match, and make sure each piece of evidence supports a specific point you intend to make.
Step 3: Include the essential transaction details
Start your chargeback rebuttal letter by clearly identifying the disputed transaction. This helps your payment processor and the issuing bank match your response to the correct case and verify the information against their records.
Include the following details at the beginning of your letter:
- Merchant information: Your business name and relevant contact information.
- Chargeback case number: The unique dispute reference provided by your processor or acquiring bank.
- Transaction date and amount: The original payment date, currency, and disputed amount.
- Order or transaction ID: The reference number that connects the payment to your internal records.
- Chargeback reason code: The code and description assigned to the dispute.
- Cardholder information: The customer’s name and relevant account or order details, where appropriate.
You can organize these details in a short table or a simple header at the top of your rebuttal letter.
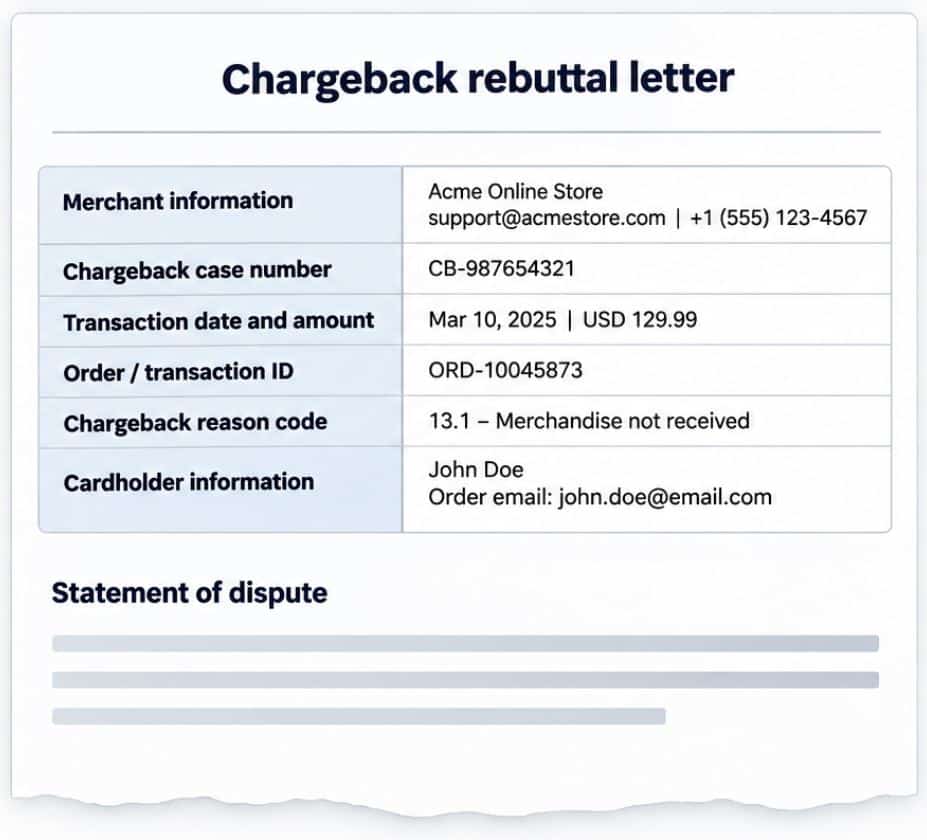
Make sure all information matches your payment records and chargeback notification. Even small inconsistencies, such as incorrect transaction dates or reference numbers, can make your evidence harder to review.
Step 4: Explain why the chargeback should be reversed
The main body of your chargeback rebuttal letter should clearly explain why you believe the transaction was valid and the chargeback is unjustified.
Start by acknowledging the customer’s claim, then present the facts that contradict it. Focus on information you can verify through transaction records, fulfillment documentation, or customer communications.
We recommend presenting events in chronological order, using specific dates and details to make your explanation easy to follow.
For example, if a customer claims they never received their order, your response might read:
The customer placed an order for a wireless headset on March 10, 2026, totaling $129.99. The order was shipped on March 11 via UPS and marked as delivered to the customer’s provided shipping address on March 14, 2026. Carrier tracking records and delivery confirmation are included as supporting evidence.
Avoid emotional language, accusations against the customer, or unsupported statements about their intentions. Your goal is not to argue with the cardholder but to demonstrate — using verifiable facts — why the chargeback should be reversed.
Keep the explanation focused on the specific dispute reason. Additional details should only be included if they help establish the validity of the transaction or directly address the customer's claim.
Step 5: Reference your supporting documents
Now it’s time to channel your inner lawyer. Label each supporting document as an exhibit (Exhibit A, Exhibit B, Exhibit C, etc.) and reference it in the relevant part of your letter. Your goal is to make the reviewer’s job easier.
For example, in a merchandise-not-received dispute, you might organize your evidence as follows:
- Exhibit A – Original order receipt: Confirms the purchase date, transaction amount, and items ordered.
- Exhibit B – Carrier delivery confirmation: Shows the tracking number, delivery date, and delivery address.
- Exhibit C – Customer communication: Contains an email from the customer acknowledging receipt of the package.
Within your letter, you can reference these documents naturally:
The order was shipped on March 11, 2026, and delivered to the customer’s provided address on March 14, 2026, as confirmed by the carrier’s delivery records (Exhibit B). The customer subsequently acknowledged receiving the package in an email dated March 15, 2026 (Exhibit C).
Attach the supporting documents separately, using clear file names and labels that match the references in your letter. Follow your processor’s requirements for file formats, document limits, and evidence submission.
Step 6: End with a clear request for reversal
Conclude your chargeback rebuttal letter by briefly summarizing why the transaction was legitimate and formally requesting that the chargeback be reversed.
For example, you could write:
Based on the transaction records, delivery confirmation, and customer correspondence provided, we believe this chargeback is unjustified. We respectfully request that the issuing bank review the supporting evidence and reverse the chargeback in our favor.
End the letter with your business name and the name and title of the authorized representative submitting the response.
Before submitting, double-check that your request is consistent with the evidence provided and that all referenced documents are included in your chargeback response package.
How to submit your chargeback response
A chargeback response is typically submitted through your payment processor or acquiring bank, using a dispute management portal.
The exact submission process varies by provider, but generally involves the following steps:
- Find the chargeback notification: Log in to your payment processor’s dashboard or review the dispute notification you received. Locate the case number, reason code, disputed amount, and response deadline.
- Prepare your response package: Combine your completed rebuttal letter with the relevant supporting evidence. Follow your processor’s requirements for document formats, file sizes, and attachments.
- Upload and submit your response: Use your processor’s dispute management portal or another approved submission method to send your rebuttal letter and evidence.
- Monitor the dispute status: Save your submission confirmation and check for updates or requests for additional information.
Your processor or acquiring bank will handle forwarding the response through the appropriate card network channels for review.
IMPORTANT: Pay close attention to the submission deadline. Response timeframes vary depending on the card network, dispute reason, and processor. Your processor may also set an earlier internal deadline to allow time for reviewing and forwarding your evidence.
This can be time-consuming, which is why many of our high-volume and high-risk merchants use tools like Chargebacks911 and Chargeflow. You can integrate any of the popular chargeback management platforms with SecreGlobalPay’s gateway to partially or fully automate the entire representment process.
Chargeback rebuttal letter samples for common dispute types
Below are practical examples covering these four common chargeback scenarios:
| Chargeback scenario | Visa reason code | Mastercard reason code |
|---|---|---|
| Unauthorized transaction | 10.4 – Other Fraud (Card-Absent Environment) | 4837 – No Cardholder Authorization |
| Merchandise not received | 13.1 – Merchandise/Services Not Received | 4853 – Cardholder Dispute (Goods or Services Not Provided) |
| Canceled subscription | 13.2 – Canceled Recurring Transaction | 4853 – Cardholder Dispute (Canceled Recurring Transaction) |
| Product not as described | 13.3 – Not as Described or Defective Merchandise/Services | 4853 – Cardholder Dispute (Not as Described or Defective) |
Each example uses a fictional transaction to demonstrate how you can structure your argument, reference supporting evidence, and request a reversal.
Example 1: Chargeback rebuttal letter for unauthorized transactions
Scenario: A customer purchases $189 worth of merchandise from an online retailer but later disputes the payment, claiming they never authorized it.
The merchant has records showing that the purchase was made through the customer’s registered account, using a previously recognized device. The merchant also has two earlier, undisputed transactions that may qualify as supporting evidence under Visa’s Compelling Evidence 3.0 rules.
Sample rebuttal letter:
Date: November 14, 2026
Merchant: Northstar Outdoor Gear
Chargeback case number: CB-2026-10482
Transaction date: October 21, 2026
Disputed amount: $189.00 USD
Order ID/Transaction ID: NS-84721
Reason code: Visa 10.4 — Other Fraud (Card-Absent Environment)
Subject: Chargeback rebuttal — Unauthorized transaction claim
Dear Dispute Resolution Team,
We are submitting this rebuttal to contest the chargeback associated with order NS-84721. Based on our transaction records, customer account activity, and previous purchase history, we believe the disputed transaction was authorized.
On October 21, 2026, the customer placed an order totaling $189.00 through our online store. The order was completed through the customer’s registered account following a successful account login.
Our records show that:
- The transaction was associated with the customer’s established account (Exhibit A).
- The account login and transaction records show a recognized device fingerprint and IP address (Exhibit B).
- Two previous purchases, completed on February 6 and May 28, 2026, used the same payment credentials, customer account ID, and device fingerprint. Neither transaction was reported as fraudulent or disputed (Exhibit C).
The previous transactions fall within the applicable historical transaction period and provide additional evidence connecting the disputed purchase to the customer’s established purchasing activity.
Based on the attached documentation, we respectfully request that the issuing bank review the evidence and reverse the chargeback.
Sincerely,
Sarah Mitchell
Disputes Manager
Northstar Outdoor Gear
disputes@northstaroutdoorgear.example
Example 2: Chargeback rebuttal letter for merchandise not received
Scenario: A customer orders a $249.99 coffee machine from an online retailer but later files a chargeback claiming the product never arrived.
The merchant has shipping records confirming that the order was dispatched on time and carrier tracking information showing that the package was delivered to the customer’s provided shipping address. The carrier also provides photographic proof of delivery.
Sample rebuttal letter:
Date: November 14, 2026
Merchant: HomeBrew Essentials
Chargeback case number: CB-2026-10835
Transaction date: October 12, 2026
Disputed amount: $249.99 USD
Order ID/Transaction ID: HB-58291
Reason code: Visa 13.1 — Merchandise/Services Not Received
Subject: Chargeback rebuttal — Merchandise not received
Dear Dispute Resolution Team,
We are submitting this rebuttal to contest the chargeback associated with order HB-58291. Our shipping and delivery records indicate that the merchandise was successfully delivered to the address provided by the customer.
The customer placed an order for a HomeBrew Espresso Machine on October 12, 2026, totaling $249.99. The order was processed and dispatched via UPS on October 13, 2026.
According to the carrier’s tracking records, the package was delivered on October 16, 2026, to the customer’s designated shipping address.
The following documentation supports our response:
- Exhibit A – Original order confirmation: Confirms the product purchased, transaction amount, order date, and shipping address supplied by the customer.
- Exhibit B – Shipping and tracking records: Shows the shipment date, carrier tracking number, and delivery status.
- Exhibit C – Proof of delivery: Includes the carrier’s delivery confirmation, delivery date, and photograph of the package at the customer’s provided address.
Based on this documentation, we believe the merchant fulfilled its obligation to deliver the purchased merchandise. We respectfully request that the issuing bank review the evidence and reverse the chargeback.
Sincerely,
Michael Carter
Customer Operations Manager
HomeBrew Essentials
support@homebrewessentials.example
Example 3: Chargeback rebuttal letter for canceled subscriptions
Scenario: A customer disputes a $49 monthly subscription charge, claiming they canceled their subscription before the payment was processed.
However, the merchant’s records show that the customer submitted their cancellation request three days after the disputed payment. The merchant also has the original subscription agreement, billing history, and cancellation confirmation to support its response.
Sample rebuttal letter:
Subject: Chargeback rebuttal — Canceled subscription dispute
Dear Dispute Resolution Team,
We are submitting this rebuttal to contest the chargeback associated with subscription CD-73821. Our billing and cancellation records show that the disputed payment was processed before the customer requested cancellation.
The customer subscribed to our monthly software plan on September 1, 2026, agreeing to recurring payments of $49.00, billed on the first day of each month (Exhibit A).
The subscription automatically renewed on October 1, 2026, and the $49.00 payment was successfully processed (Exhibit B).
Our account records show that the customer submitted a cancellation request on October 4, 2026, three days after the disputed transaction. The cancellation was confirmed immediately, and the subscription was scheduled to expire on October 31, 2026, with no further renewal charges (Exhibit C).
The customer retained access to the service for the remainder of the paid billing period, in accordance with the subscription terms accepted at signup.
Based on the documented billing timeline and cancellation records, we believe the October 1 transaction was valid. We respectfully request that the issuing bank review the attached evidence and reverse the chargeback.
Sincerely,
Emily Roberts
Billing Operations Manager
ClarityDesk Software
billing@claritydesk.example
Example 4: Chargeback rebuttal letter for products not as described
Scenario: A customer purchases a $89 set of curtains from an online home decor retailer but later files a chargeback, claiming the curtains were advertised as 100% linen but were actually made from polyester.
The merchant has a copy of the original product listing, which clearly identifies the curtains as 100% polyester, along with the customer’s order confirmation and fulfillment records showing that the correct product was shipped.
Sample rebuttal letter:
Date: November 14, 2026
Merchant: Coastal Home Décor
Chargeback case number: CB-2026-11057
Transaction date: October 9, 2026
Disputed amount: $89.00 USD
Order ID/Transaction ID: CH-62941
Reason code: Visa 13.3 — Not as Described or Defective Merchandise/Services
Subject: Chargeback rebuttal — Product not as described
Dear Dispute Resolution Team,
We are submitting this rebuttal to contest the chargeback associated with order CH-62941. Our product listing, order confirmation, and fulfillment records demonstrate that the merchandise delivered matched the product description available to the customer at the time of purchase.
On October 9, 2026, the customer purchased a set of Linen-Look Curtains for $89.00 through our online store.
The customer subsequently claimed that the curtains were advertised as 100% linen but were made from polyester.
However, the original product listing explicitly identified the curtains as “Linen-Look Curtains — 100% Polyester.” The materials were disclosed in the product specifications before checkout (Exhibit A).
The order confirmation dated October 9, 2026, identifies the purchased product and its specifications (Exhibit B). Our fulfillment records confirm that the same product, including the matching SKU and material specifications, was shipped and delivered on October 14, 2026 (Exhibit C).
Based on the documentation provided, the merchandise matched the advertised product description and the customer’s original order.
We respectfully request that the issuing bank review the supporting evidence and reverse the chargeback.
Sincerely,
Daniel Foster
Customer Service Manager
Coastal Home Décor
support@coastalhomedecor.example
Minimize future chargebacks with SecureGlobalPay
Contesting invalid chargebacks can help you recover lost revenue, but preventing unnecessary disputes in the first place is often the better strategy.
At SecureGlobalPay, we help high-risk and high-volume merchants reduce fraud, manage chargebacks, and protect their payment processing operations through a combination of advanced technology and personalized support.
Our solutions include:
- Chargeback alerts: Get early notifications through Ethoca and Verifi solutions, giving you an opportunity to resolve eligible disputes before they become formal chargebacks.
- Rapid Dispute Resolution (RDR): Automatically resolve eligible Visa disputes based on predefined rules, reducing manual work and preventing qualifying cases from progressing into chargebacks.
- Advanced fraud prevention: Use 3D Secure authentication, Address Verification Service (AVS), CVV checks, and AI-powered fraud detection to identify suspicious transactions.
- Convenient integrations: Our gateway seamlessly integrates with many popular chargeback management tools.
- Dedicated account management: Work with an experienced account manager who can help you monitor processing activity, identify potential risks, and configure chargeback prevention tools.
- High-risk payment processing: Access merchant accounts and payment gateway solutions designed for businesses that face elevated fraud and chargeback risks.
Our team can help you choose and configure the right combination of tools based on your industry, transaction volume, and chargeback history.
If you need a merchant account or are planning to switch providers, you can apply online here or send your questions to partners@secureglobalpay.net.
Written by Roland G. Szasz - Director of Business Development - 25+ years in payment processing.
Roland has spent nearly three decades helping businesses navigate the complexities of payment processing. He now works closely with high-risk merchants that have been declined or restricted by conventional providers - and shares his experience and best practices on this blog.
FAQs
A chargeback rebuttal letter should include the merchant’s information, transaction details, chargeback case number, reason code, a clear explanation of why the dispute is invalid, references to supporting evidence, and a formal request for reversal.
Ideally, a chargeback rebuttal letter should be one page or less. Focus on relevant facts and keep detailed supporting documentation in separate attachments. More complex disputes may require longer explanations.
Yes, you can use the same basic structure, but each response should be customized to address the specific chargeback reason code, transaction details, and available evidence. One generic response will be effective across different dispute types.
Include documentation that directly addresses the customer’s claim. Common examples include transaction receipts, authentication records, delivery confirmations, customer communications, subscription agreements, and refund records. Evidence requirements vary by card network and dispute reason.
Response deadlines vary by card network, reason code, and payment processor. On average, merchants have 7–30 days to submit their evidence. Always follow the specific deadline stated in your chargeback notification.
No. Submitting a rebuttal letter does not guarantee that the chargeback will be reversed. The outcome depends on the strength and relevance of your evidence, applicable card network rules, and the issuing bank’s judgment of the dispute.

Tailored payment solutions for high-risk merchants
- Domestic and offshore accounts
- Competitive, interchange plus pricing
- No long-term contracts or hidden fees
- Built in fraud protection
- Dedicated account manager; 24/7
Sign up in 5 minutes
A+ Rating
as of 06/17/26