


Home » How to Set Up an Offshore Merchant Account and Payment Processing

How to Set Up an Offshore Merchant Account and Payment Processing
| August 11, 2019
Offshore merchant accounts are often associated with high-risk businesses that struggle to find payment processing at home. While offshore acquiring can provide additional options for some high-risk merchants, it is not as simple as getting rejected by a U.S. bank and opening a merchant account in another country.
Visa and Mastercard have rules governing where a merchant can legitimately be located for payment processing purposes, especially for card-not-present transactions.
Because of that, offshore payment processing makes the most sense for international businesses that have, or are prepared to establish, a legitimate presence in another market. That can include high-risk merchants, ecommerce businesses expanding internationally, multinational companies, and merchants looking for acquiring arrangements that better support particular markets, currencies, or business models.
SecureGlobalPay helps eligible merchants set up offshore merchant processing by connecting them with our international acquiring partners and providing a robust payment gateway that can handle most card brands and currencies.
If you’re planning to open an offshore merchant account, this article explains who qualifies, the steps involved, and important considerations.
QUICK TAKEAWAYS
- An offshore merchant account uses an acquiring relationship outside your primary home market, but you must legitimately qualify for acquiring in that jurisdiction.
- Visa and Mastercard merchant-location rules generally require genuine business presence; a shell company, virtual office, or foreign bank account alone is often not enough.
- Requirements may include a local company, operations, licenses, tax registrations, a bank account, an authorized signer, or a guarantor, depending on the country and acquirer.
- High-risk merchants can use offshore acquiring, but it is not simply an alternative when they cannot obtain domestic processing.
- SecureGlobalPay can help merchants set up an international bank account in a favorable jurisdiction and integrate their payment system with the offshore bank and processor for seamless operations.
What is an offshore merchant account?
An offshore merchant account is a merchant acquiring account established with an acquiring bank or financial institution outside the business’s primary home market. For example, a UK-based company that qualifies for U.S. acquiring could establish a merchant account with a U.S. acquiring bank — and vice versa.
The exact process depends on the local banking and underwriting requirements. U.S. acquirers are likely to ask a foreign-owned merchant for a U.S. signer, SSN/ITIN information, residency information, local representation, credit checks, or a personal guarantee, while a U.S. company establishing itself in the UK will need to deal with UK company registration, VAT, banking, and overseas-owner verification requirements.
Opening an offshore merchant account requires you to show that your business legitimately qualifies for acquiring in that jurisdiction and then satisfy the acquiring bank’s underwriting requirements.
The exact requirements vary by country, industry, and acquirer. You may need the following:
| REQUIREMENT | WHAT TO EXPECT |
|---|---|
| Qualifying business presence | To qualify, you need genuine business activity that supports treating your company as a merchant in that country. Foreign corporation, virtual office, PO box, local server, or registered agent generally does not establish sufficient business presence by itself. |
| Local legal entity | Often required by the acquirer. Depending on jurisdiction, you will need to provide a certificate and articles of incorporation, company registration and tax numbers, ownership structure, and details of directors and beneficial owners. |
| Licenses and permits | Any registrations or licenses required to legally operate your business in a specific jurisdiction. |
| Tax registration | Applicable income, sales, VAT, GST, or other tax registrations. Mastercard specifically includes applicable local income and indirect-tax compliance among its merchant-location requirements. |
| Business bank account | An account the acquirer can use to settle your processing funds. Some providers support settlement into accounts elsewhere or in multiple currencies, while others require a local bank account. |
| KYC and ownership documents | Identification and ownership information for directors and beneficial owners. |
| Financial and processing records | Bank statements, previous processing statements, and information about sales and chargebacks. |
| Compliant website | Clear pricing, policies, contact information, and accurate descriptions of what you sell. |
| Authorized signer or guarantor | Some acquiring banks may require an authorized representative or personal guarantee. |
Many businesses have a hard time figuring out if they qualify, and even if an offshore merchant account is right for them. If you’re in the same boat, reach out to SecureGlobalPay — tell us what you’re considering, and we will give you expert recommendations.
Who uses offshore merchant accounts?
Offshore merchant accounts are most relevant to businesses with a legitimate reason to establish an acquiring relationship outside their primary home market. This often includes:
- International ecommerce businesses: Companies selling across multiple countries may use international acquiring to better support different markets, currencies, and payment flows.
- Multinational businesses: Companies with subsidiaries, employees, offices, or other operations in multiple countries may maintain merchant accounts in more than one jurisdiction.
- Businesses expanding into new markets: A company establishing genuine operations in another country may seek local acquisition as part of that expansion. Depending on the jurisdiction and acquirer, this can require a local entity, bank account, tax registration, or other business presence.
- High-risk merchants: Some international acquirers specialize in industries that mainstream domestic banks are unwilling to support. However, being rejected domestically does not automatically make a merchant eligible for an offshore account; the business still has to qualify for acquiring in that jurisdiction.
- Businesses that need specialized acquiring: Some merchants look internationally for support for specific currencies, countries, business models, transaction volumes, or payment requirements their domestic providers cannot accommodate.
- Multi-entity and high-volume businesses: Larger merchants may use multiple acquiring relationships to support different entities, brands, regions, or payment strategies and reduce dependence on a single provider.
The location of your customers does not necessarily determine where your merchant account should be based. An e-commerce business headquartered in the UK that sells worldwide might still use the UK as its principal merchant location; it will just have a high volume of cross-border transactions.
How does offshore credit card processing work?
Offshore payment processing works through the same basic card payment infrastructure as domestic processing.
The only difference is that, when a customer makes a payment, funds are processed through the chosen foreign bank instead of a domestic bank, before being transferred to your account.
Now, your offshore bank will still have its own rules and terms related to fees and chargebacks — just the same as a local US bank would.
If you sign up with SecureGlobalPay, you’ll get access to a secure payment gateway that can be configured (currencies, regions, payment routing…) to suit the offshore credit card processing requirements of your acquiring bank, whether at home or abroad.
QUICK AND EASY ONLINE APPLICATION
Start Accepting OffShore Payments Now!
How to open an offshore merchant account?
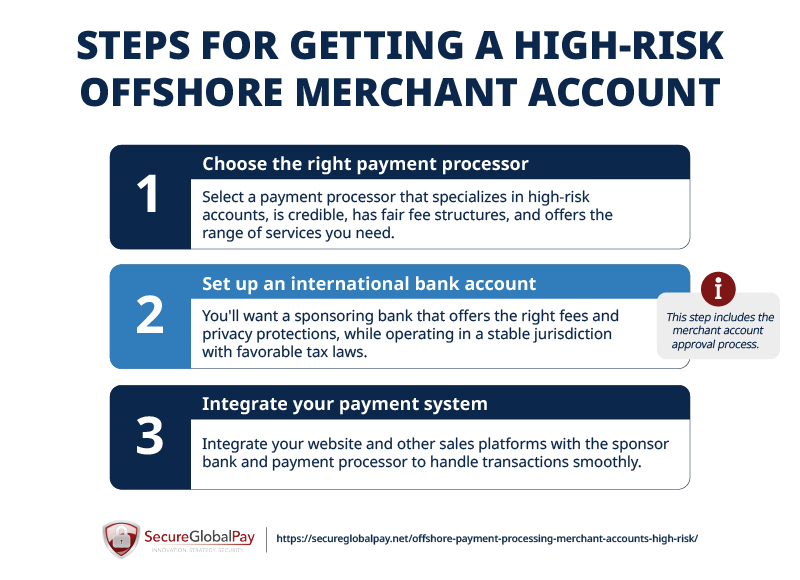
There are three steps for setting up a high-risk offshore merchant account:
- Choose a payment processor: Select a payment processor that specializes in high-risk accounts and has robust experience handling the regulatory requirements of your target offshore location. Research potential processors thoroughly to check their credibility, fee structures, and the range of services they offer.
- Set up an international bank account: This bank should be in a jurisdiction that is favorable to your business type and offers economic stability, favorable tax laws, and privacy protections. Evaluate their international services, associated fees, and compatibility with your business operations.
- Integrate your payment system: This step involves setting up the technical aspects of your payment processing. It includes integrating your website and other sales platforms with the sponsor bank and your payment processor to handle transactions smoothly.
The actual merchant account approval process is essentially the same as when applying for a US merchant account. Card processing payment underwriters look for the same type of information.
While the exact documentation can vary from country to country, usually, you will need:
- Government-issued ID like a driver’s license or EIN from the IRS (or both)
- Voided check from your regular business bank account
- Financial statements covering, at a minimum, the last 3 months
- Memorandum and Articles of Association (if looking to open a merchant account in the UK)
- Proof of available funds
After you provide the required documentation, an offshore payment processor will review everything, go through your merchant processing statement, estimate your potential chargeback ratio, and similar.
The exact process depends on the local banking and underwriting requirements. U.S. acquirers are likely to ask a foreign-owned merchant for a U.S. signer, SSN/ITIN information, residency information, local representation, credit checks, or a personal guarantee, while a U.S. company establishing itself in the UK will need to deal with UK company registration, VAT, banking, and overseas-owner verification requirements.
The whole approval process for a high-risk merchant takes 2 to 7 business days on average, if underwriters don’t find any major issues.
If you decide to use SecureGlobalPay as your payment service provider, we will advise you of what a specific underwriter may require once we have matched you with a suitable offshore partner bank.
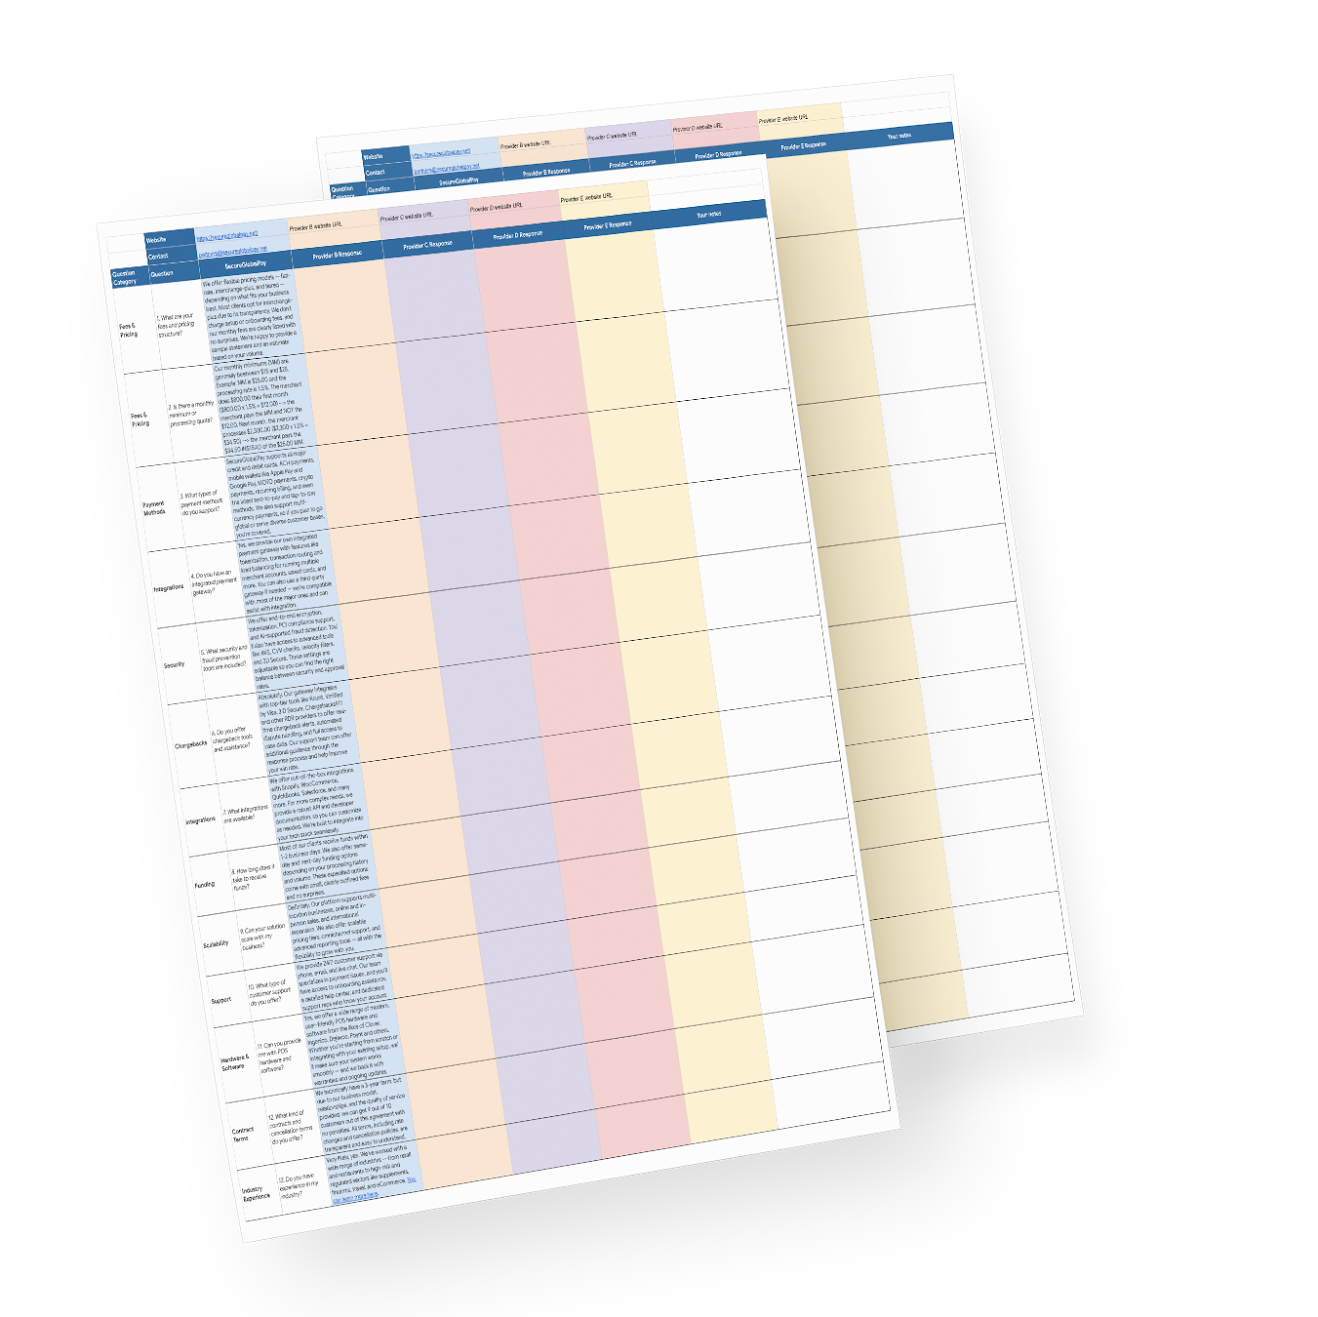
Free Template for Comparing Merchant Service Providers
Our Google Sheet template arms you with 13 critical questions you should ask each provider to catch red flags and cut through the sales talk — with SecureGlobalPay’s answers already filled in for comparison.
How card scheme rules restrict offshore payment processing
Card scheme rules are the operating standards set by payment networks such as Visa and Mastercard. They govern how merchants, acquiring banks, processors, and other participants use the card networks, including rules around merchant location, transaction data, fraud, chargebacks, security, and certain high-risk business categories.
For offshore payment processing, these rules help determine whether a merchant can legitimately be acquired in a particular country and how that merchant must be represented in card transactions. They can require a genuine business presence in the acquiring jurisdiction and accurate merchant-location and business information.
Individual acquiring banks often impose even stricter requirements, such as local bank accounts, guarantors, reserves, or geographic sales thresholds.
For example, let’s imagine you are an EU resident who got an ITIN (Individual Taxpayer Identification Number) because you want to conduct business in a different region under a US Corporation and EIN. That alone is not enough to open an offshore merchant account. You also need verifiable residency in the States or an authorized representative with US residency who can act on your behalf. The same goes for a US citizen opening a merchant account in Europe.
Open a high-risk offshore merchant account with SecureGlobalPay
While we can work with almost any industry, SecureGlobalPay specializes in helping high-risk and high-volume merchants accept and process payments quickly and effectively.
For those who need offshore merchant services, we offer the following:
- Fast approval for an offshore merchant account through our industry connections with offshore sponsoring banks.
- Dedicated account manager with 20+ years of industry experience who will guide you throughout the whole setup and approval process.
- Access to our secure offshore payment gateway that supports 100+ currencies and integrates with over 200 shopping carts, eCommerce platforms, chargeback tools, CRMs, invoicing software, and other business systems.
- Advanced chargeback dispute resolution and prevention programs.
- Fair and flexible processing fees that don’t ruin your bottom line.
Learn more by sending a question to partners@secureglobalpay.net or simply fill out our online application form.
Written by Roland G. Szasz - Director of Business Development - 25+ years in payment processing.
Roland has spent nearly three decades helping businesses navigate the complexities of payment processing. He now works closely with high-risk merchants that have been declined or restricted by conventional providers - and shares his experience and best practices on this blog.
Offshore payment processing FAQ
An offshore merchant is typically a business owner who has opted to register and use a merchant account in a foreign country.
This happens because banking rules and underwriters’ guidelines regarding risk differ. More importantly, the major card networks also apply different rules in different countries.
For example, the Visa operating rules manual consists of 765 pages covering what partner acquiring banks can and can’t do as regards payment processing. Visa has split the world into 5 regions, and rules vary in each region. A line of business that Visa will not handle in the US could well be acceptable in, say, Europe. MasterCard operates along similar lines.
Offshore payment processors are like international banks. It just means that your merchant account is with a bank in another country. For example, when a US business operates an offshore merchant account in Switzerland, the Swiss account is regarded as an offshore account for the American business.
Not always. Some acquiring banks accept businesses incorporated elsewhere, while others require a local company, bank account, director, or operational presence. Requirements depend on the jurisdiction and the acquiring partner.
Not in every case. Some offshore merchant accounts can settle funds to an approved domestic or multicurrency business account, while others require a foreign settlement account. Your offshore merchant account provider should confirm this before you apply or sign any contract.
It can be. Offshore accounts may involve higher processing rates, cross-border fees, currency-conversion costs, and longer settlement periods. Total pricing depends on your industry, volume, currencies, and risk profile.
No. Using an offshore processor does not remove your domestic tax, licensing, or reporting obligations. Depending on your business structure and account location, it may create additional filing requirements, so consult a qualified tax professional.

Posted in - International Payment Processing
Tailored payment solutions for high-risk merchants
- Domestic and offshore accounts
- Competitive, interchange plus pricing
- No long-term contracts or hidden fees
- Built in fraud protection
- Dedicated account manager; 24/7
Sign up in 5 minutes
A+ Rating
as of 06/17/26